Last Updated: November 6, 2026
Quick Summary
NRI wealth creation works best when you treat your India-based investments as a separate portfolio with its own goals, currency and time horizon, splitting every rupee across safety, growth and legacy layers. Match each asset to a specific horizon, review allocation yearly, and keep currency risk visible rather than buried.
- Split investments into three layers: safety for 0-3 years, growth for 5-15 years, and legacy for 15+ years.
- Equity mutual funds held more than 12 months are generally treated as long-term capital gains in India.
- NRE account interest is generally exempt in India, while NRO account interest is taxable.
- Update your mutual fund platform KYC after moving abroad to avoid frozen redemptions.
- Compare nominal INR returns with actual post-conversion proceeds, since a weaker rupee reduces dollar gains.
Table of Contents
- Building Long-Term Wealth as an NRI: The Core Framework
- US-Based NRI Investment Options in India: A Side-by-Side Comparison
- Mutual Funds for NRIs: SIPs, Returns, and Tax Treatment
- How an NRI SIP Calculator Helps You Plan a Rupee Corpus
- Red Sandalwood Farmland: A Timber Asset for Legacy Wealth
- Repatriating Capital from Indian Land Sales: Rules and Documentation
- Download the NRI Guide to Start Your Investment Plan
- Frequently Asked Questions
Building Long-Term Wealth as an NRI: The Core Framework
NRI wealth creation starts with a simple discipline: treat your India-based investments as a separate portfolio with its own goals, currency, and time horizon, not as an extension of your US accounts. Investors who define the rupee corpus they need, match each asset to a specific horizon, and keep documentation clean from day one tend to end up with far fewer surprises than those who chase products.
A useful way to structure the thinking is to split every rupee you invest into three layers:
| Layer | Purpose | Typical Horizon | What Belongs Here |
|---|---|---|---|
| Safety | Capital preservation, emergency needs | 0-3 years | NRE/NRO deposits, short-term debt |
| Growth | Beat inflation, build the corpus | 5-15 years | Equity mutual funds, SIPs |
| Legacy | Transferable, hard assets | 15+ years | Registered farmland, timber assets |
The framework matters more than any single product. NRIs building NRI wealth steadily tend to revisit asset allocation each year, adjust for risk tolerance as retirement approaches, and keep currency risk visible rather than buried. That last point is where most portfolios quietly underperform.
US-Based NRI Investment Options in India: A Side-by-Side Comparison
No single option wins across every goal. The honest comparison looks like this:
| Option | Liquidity | Risk Level | Tax Efficiency | Best For |
|---|---|---|---|---|
| NRE fixed deposit | High | Low | Interest tax-free in India | Parking funds, short goals |
| NRO deposit | High | Low | Interest taxable in India | Managing India-sourced income |
| Mutual funds via SIP | Medium-High | Market-linked | Depends on holding period | Long-term growth |
| Life insurance plans | Low | Varies | Mixed | Guaranteed savings, protection |
| Real estate | Low | Moderate | Depends on structure | Rental income, capital appreciation |
| Timber farmland | Very low | Illiquid, long-dated | Depends on structure | Legacy wealth, diversification |
Pros of market-linked routes: transparency, daily liquidity, easy SIP discipline. Cons: returns follow markets, and currency moves can erase rupee gains. Pros of land-based assets: tangible ownership, inflation-linked pricing in the underlying commodity, and a genuine diversifier. Cons: illiquidity and long horizons. For a deeper look at how timber yield structures work, read our guide to timber yield investment for NRIs.
Mutual Funds for NRIs: SIPs, Returns, and Tax Treatment
Mutual funds for NRIs remain the most accessible growth engine. A systematic investment plan, or SIP, is a fixed amount invested at regular intervals into a chosen fund, which smooths entry price across market cycles. Equity funds suit long horizons; debt funds suit capital preservation and shorter goals.
Three practical points most guides underplay:
- Account type changes the tax treatment. NRE accounts are generally used for fresh remittances, while NRO accounts hold India-sourced income. Confirm your fund platform accepts your residency status and country before you start a SIP.
- Repatriation rules differ by account and by fund type. Keep statements, bank records, and purchase confirmations organized from the first installment.
- Fund selection beats fund count. A handful of well-chosen equity and debt funds, reviewed annually, is easier to manage than a scattered portfolio.
Watch out: starting a SIP from an NRO account without checking how gains will be taxed and repatriated later is one of the most common compliance mistakes we see.
How the tax treatment actually works
For a US-based NRI, the Indian tax outcome generally depends on three things: the account the investment sits in, the holding period, and whether a treaty provision applies. The following general pattern applies in many cases:
- Equity mutual funds held more than 12 months are generally treated as long-term capital gains, while shorter holdings are short-term. Confirm current rules for the applicable tax year with a qualified advisor.
- NRE account interest is generally exempt in India for a qualifying non-resident, while NRO account interest is taxable in India, usually with tax withheld at source by the bank.
- Withholding at source applies to many India-sourced payments to non-residents. The rate depends on the income type and on whether you have filed the paperwork to claim treaty benefits.
- Treaty relief is available under the US-India income tax treaty, but it is not automatic. You generally need a Tax Residency Certificate from the IRS or a comparable document, plus the appropriate Indian forms, before the lower treaty rate is applied.
The compliance checklist most guides skip
Before your first SIP, confirm the following are in place:
- PAN linked to your current passport and residency status
- KYC updated with your overseas address and tax residency
- FATCA/CRS self-declaration filed with the fund platform or bank
- NRE or NRO account correctly designated for the source of funds
- Tax Residency Certificate ready if you intend to claim treaty benefits
- Records of every remittance that funded the investment
A common pattern is for NRIs to update their bank KYC after moving abroad but forget to update the mutual fund platform, which can freeze redemptions at the worst possible time. Treat the checklist as a yearly review, not a one-time task.
Currency risk is part of the return
A rupee gain is not a dollar gain. If the rupee weakens against the dollar, the dollar value of your redemption falls even when the fund's NAV rises. Compare the nominal INR return with the proceeds you would actually receive after conversion and fees. For long-horizon goals, a weaker-rupee scenario should still leave the plan intact; if it does not, the allocation is too aggressive for the goal.
How an NRI SIP Calculator Helps You Plan a Rupee Corpus
An NRI SIP calculator is a projection tool that estimates how a fixed monthly investment could grow over time at an assumed rate of return. It converts vague intentions into a target number.
Use it in three steps:
- Set the goal. Decide the rupee corpus you want, and by when. Retirement planning and a child's education usually sit 10-20 years out.
- Work backwards. Enter a realistic expected return and see the monthly SIP required. Run a conservative and an optimistic case.
- Stress-test for currency. Convert the projected rupee corpus into your home currency at today's rate and at a weaker rate. If the weaker case still meets your goal, the plan is resilient.
The calculator is a planning aid, not a promise. Returns vary, and disciplined regular investing over a long investment horizon matters more than picking a perfect number.
Red Sandalwood Farmland: A Timber Asset for Legacy Wealth
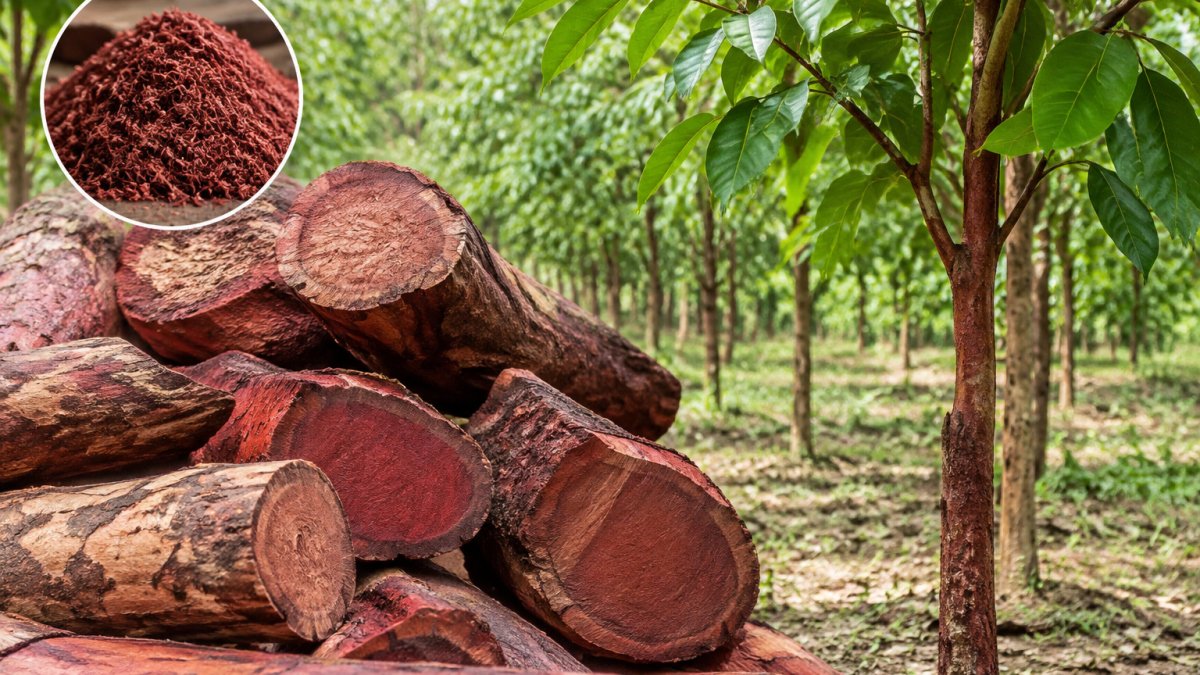
Red sandalwood farmland is a long-dated, physical asset: registered agricultural land planted with red sandalwood trees, managed professionally, and harvested at maturity. The appeal sits in the wood itself.
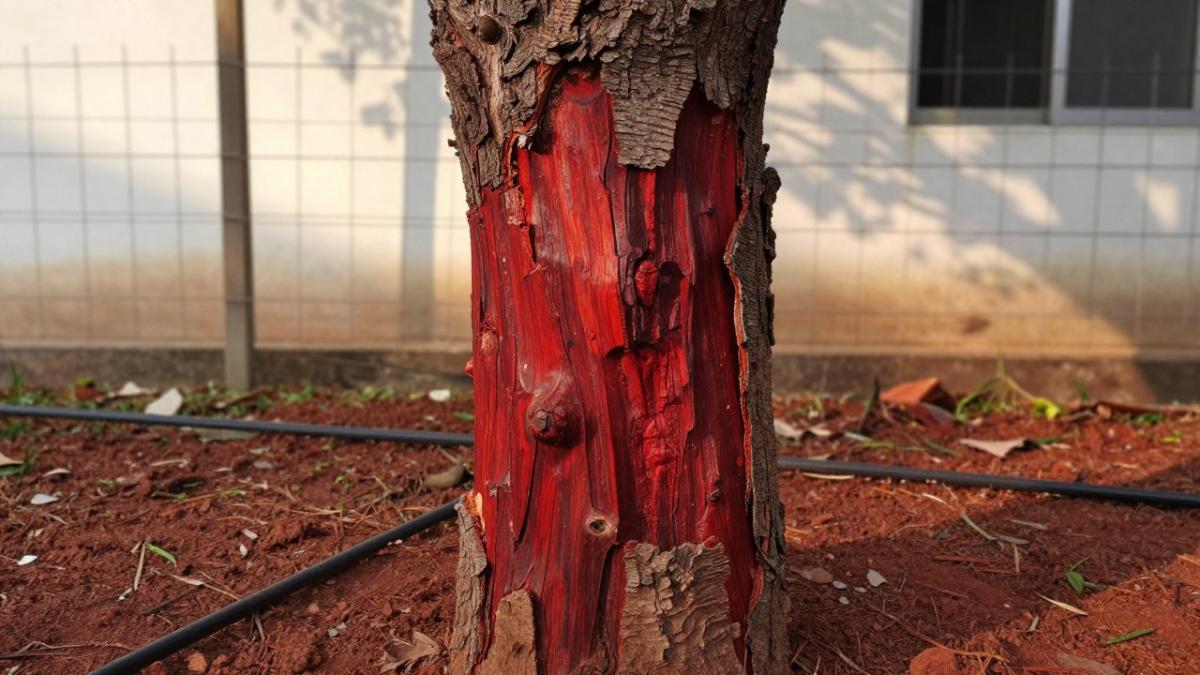
Red sandalwood is a slow-growing, protected species with tightly controlled legal trade, so supply cannot expand quickly. Demand projections for coming years should be checked against current market sources, and no one can promise a specific price at harvest.
At RedGoldAgro, each unit includes 1,066 square yards of registered patta land and 104 red sandalwood trees, with drip irrigation, 24/7 security, FEMA-compliant ownership, and a 60/40 timber yield share at maturity. Every tree is tagged and logged with the Forest Department. For the full process, see how to invest in red sandalwood farmland.
Best for: NRIs seeking a hands-off, long-horizon legacy holding. Skip if: you may need the capital within a few years.
Repatriating Capital from Indian Land Sales: Rules and Documentation
Repatriating capital from Indian land sales depends on how the property was acquired and which account received the funds. Sale proceeds from property bought with foreign remittance through an NRE account follow a different path than proceeds from inherited or rupee-funded land. The paperwork is the whole game.
The two tracks
- Foreign-funded property. If the land was purchased using funds remitted from abroad through banking channels and the original investment was repatriable, sale proceeds are generally repatriable, subject to payment of applicable taxes and submission of the original purchase and remittance evidence.
- Rupee-funded or inherited property. Proceeds from property acquired in rupees, or received as inheritance, generally fall under the NRO route. Repatriation is permitted up to the limits set by the Reserve Bank of India, after payment of taxes and with the required undertaking and certificate from a chartered accountant. Confirm current limits with your bank.
The documentation set
Keep this ready before you sell:
- Original purchase deed and registration records
- Proof of the remittance that funded the purchase (for foreign-funded property)
- Bank statements showing the sale proceeds credited
- Tax filings and capital gains computation
- Certificate of remittance from your authorized dealer bank
- Form 15CA and Form 15CB where the transaction involves a remittance and requires a chartered accountant's certification
- Undertaking and declaration in the format required by the bank for NRO repatriation
How the process runs
The authorized dealer bank is the gatekeeper. You submit the documentation set, the bank verifies the source of funds and the tax position, and the remittance is processed through the bank's foreign exchange channel. The timeline often depends on how complete the file is at first submission; a missing remittance proof or an unsigned undertaking can add delays.
Watch out: selling land that was purchased with a mix of NRE and rupee funds without documenting the split is one of the most common reasons a repatriation request is partially rejected. Reconstruct the funding history before you list the property, not after.
What changes year to year
Repatriation caps, forms, and bank checklists are updated periodically. Confirm the current requirements with your bank and a qualified advisor before initiating a transfer, and keep a copy of every submission. Our walkthrough on repatriating capital from Indian land sales covers the process step by step.
Download the NRI Guide to Start Your Investment Plan
Start with clarity, not a purchase. Decide your goal, your horizon, and your currency tolerance, then match assets to each. If red sandalwood farmland fits your legacy layer, request the NRI Investment & Legacy Guide to see the full structure, documentation, and yield-sharing terms. You can also contact RedGoldAgro to arrange a farm visit and review the paperwork in person.
Frequently Asked Questions
What is the LTCG tax rate for NRIs on Indian investments?
Long-term capital gain treatment for NRIs depends on the asset type and holding period, and rates change over time. Always consult a cross-border tax advisor, as the US also taxes global income, and treaty benefits may apply.
Can US-based NRIs invest in Indian mutual funds?
Yes, US-based NRIs can invest in Indian mutual funds, but they must complete KYC with their PAN card, and some fund houses may have their own onboarding requirements. It is best to check with the fund house directly. Many NRIs use SIPs to average out currency fluctuations and build a rupee corpus over time.
How can NRIs repatriate investment proceeds from India?
NRIs can repatriate proceeds from the sale of Indian assets, including land, after paying applicable taxes. For land sales, funds are generally credited to an NRO account first, and repatriation is subject to limits and documentation requirements set by the authorized dealer bank and applicable regulations. Confirm current requirements with your bank and a qualified advisor.
What should NRIs consider before investing in Indian real estate?
NRIs should verify title deeds, check FEMA compliance, and understand exit options before investing in Indian real estate. Agricultural land purchases require specific approvals, and timber assets like red sandalwood have long maturity periods. Consider currency risk, liquidity, and whether the asset is fully managed. RedGoldAgro's red sandalwood offering is described in its own materials, and prospective investors should review the documentation directly with the company.
Building a rupee portfolio from abroad is not complicated, but it rewards patience and clean records. RedGoldAgro gives NRIs a fully managed route into registered red sandalwood farmland, with FEMA-compliant ownership, Forest Department-tagged trees, and a 60/40 timber yield share at maturity. Get started with RedGoldAgro and build a legacy asset you can document, verify, and pass on.
Download NRI Guide Add redgoldagro.com as a preferred source on Google →