Table of Contents
- Who Can Repatriate Capital from Indian Land Sales
- Documents for Repatriating Property Sale Proceeds
- NRO Account Repatriation Limit and Permitted Routes
- Form 15CA and Form 15CB for Property Sale
- Taxes on Repatriating Capital: TDS and Capital Gains
- NRI Sale of Agricultural Land in India: Special Rules
- Step-by-Step Repatriation Process and Common Pitfalls
- Conclusion
- Frequently Asked Questions
Last Updated: October 21, 2026
Who Can Repatriate Capital from Indian Land Sales
Repatriating capital from Indian land sales means moving sale proceeds out of India through authorized banking channels after tax clearance. The rules differ sharply by seller status, which decides how much you can send abroad and how quickly.
Non-Resident Indians (NRIs) and Overseas Citizens of India (OCI) hold the clearest path. Under the foreign exchange framework administered by the Reserve Bank of India, an NRI or OCI who sells residential or commercial property in India may repatriate the proceeds, subject to documentation and tax clearance.
Eligibility is not automatic access. You can be fully eligible and still have a bank reject the remittance because the paperwork chain is incomplete, a common failure among sellers who assume the sale deed alone is enough.
The practical eligibility matrix looks like this:
| Seller Status | Repatriation Allowed | Key Condition |
|---|---|---|
| NRI | Yes, up to USD 1 million per financial year | Tax clearance and NRO account route |
| OCI cardholder | Yes, same limits as NRI | Property acquired per FEMA rules |
| Foreign national of non-Indian origin | Restricted | Prior RBI approval generally required |
| Person resident in India | Not applicable | Funds already domestic |
If you are buying Indian land specifically to build a repatriable legacy asset, this guide explains how the exit actually works.
Documents for Repatriating Property Sale Proceeds
Banks want a paper trail connecting the original purchase to the current sale. A missing link can stall the remittance for months.
The documents for repatriating property sale proceeds typically include:
- Original purchase deed and current sale deed, both registered
- Property title certificate showing clear, unencumbered ownership
- PAN card and passport of the seller
- NRO account statements showing the sale proceeds credited
- Tax Deducted at Source (TDS) certificate from the buyer
- Capital gains computation prepared by a chartered accountant
- Form 15CA and Form 15CB
- Tax return acknowledgment and proof of tax paid
- Bank's own repatriation request form
Source of funds matters as much as the sale. For inherited or gifted property, banks ask for the inheritance certificate, will, or gift deed. A common mistake is submitting a sale deed without the original purchase deed, the bank cannot verify acquisition cost, and the file goes back.
Watch Out Selling inherited property without first obtaining a succession certificate or probate (where required) will block repatriation entirely. The bank treats unclear title as a compliance risk and will not remit funds until ownership is legally established in your name.NRO Account Repatriation Limit and Permitted Routes
The NRO account repatriation limit is USD 1 million per financial year for NRIs and OCIs, measured from April to March. Sale proceeds of immovable property must first land in an NRO account; they cannot be credited directly to an NRE account.
Planning to repatriate your Indian property sale money? 🛑 Hold on!
NRI Money Clinic
The USD 1 million cap covers all permissible NRO credits combined, not just property sales. Rental income, dividends, or pension repatriated in the same financial year count toward the same ceiling, so plan the timing of a large property exit accordingly.
Permitted routes for moving the money:
- NRO to foreign account directly: the standard route, supported by Form 15CA and 15CB
- NRO to NRE: allowed only for current income, not for property sale proceeds
- Reinvestment in India: no remittance needed, and certain capital gains exemptions may apply
According to Reserve Bank of India foreign exchange guidance, remittances must be routed through an authorized dealer bank, and the bank is responsible for verifying the tax clearance before processing. That makes your bank the gatekeeper, not a formality.
Form 15CA and Form 15CB for Property Sale
Form 15CA and Form 15CB for property sale are the tax clearance pair every bank requires before remitting funds abroad. Form 15CB is a chartered accountant's certificate confirming the tax treatment; Form 15CA is your declaration filed online with the tax department.
Sequence matters: your accountant issues 15CB first, analysing capital gains and applicable tax; you then file 15CA electronically with the 15CB reference; only then does the bank process the remittance.
There are exceptions. If the remittance is below the threshold set by the tax rules, or if the remitter has obtained a certificate from the tax officer, Part A of Form 15CA may suffice without 15CB. Because these thresholds change, verify the current requirement with your accountant or the Income Tax Department e-filing portal before filing.
Pro Tip Get Form 15CB prepared before you list the property, not after. Your accountant can then structure the sale timing around long-term versus short-term holding periods, which changes the tax rate and, in turn, how much capital actually leaves India.Taxes on Repatriating Capital: TDS and Capital Gains
Tax is deducted before the money reaches your account, so the amount you repatriate is always net of tax. Two layers apply: TDS withheld by the buyer, and capital gains tax on the profit.
Layer 1: TDS withheld by the buyer. Under the Income-tax Act, the buyer withholds tax on the sale consideration when the seller is a non-resident, at a higher default rate than for residents.
Layer 2: Capital gains tax on the profit. The gain is sale consideration minus acquisition cost (indexed where applicable) minus eligible improvement costs and transfer expenses.
Double taxation relief. The United States taxes its residents on worldwide income, but the IRS guidance on foreign tax credits allows you to claim a credit for tax paid in India, avoiding taxation of the same gain twice.
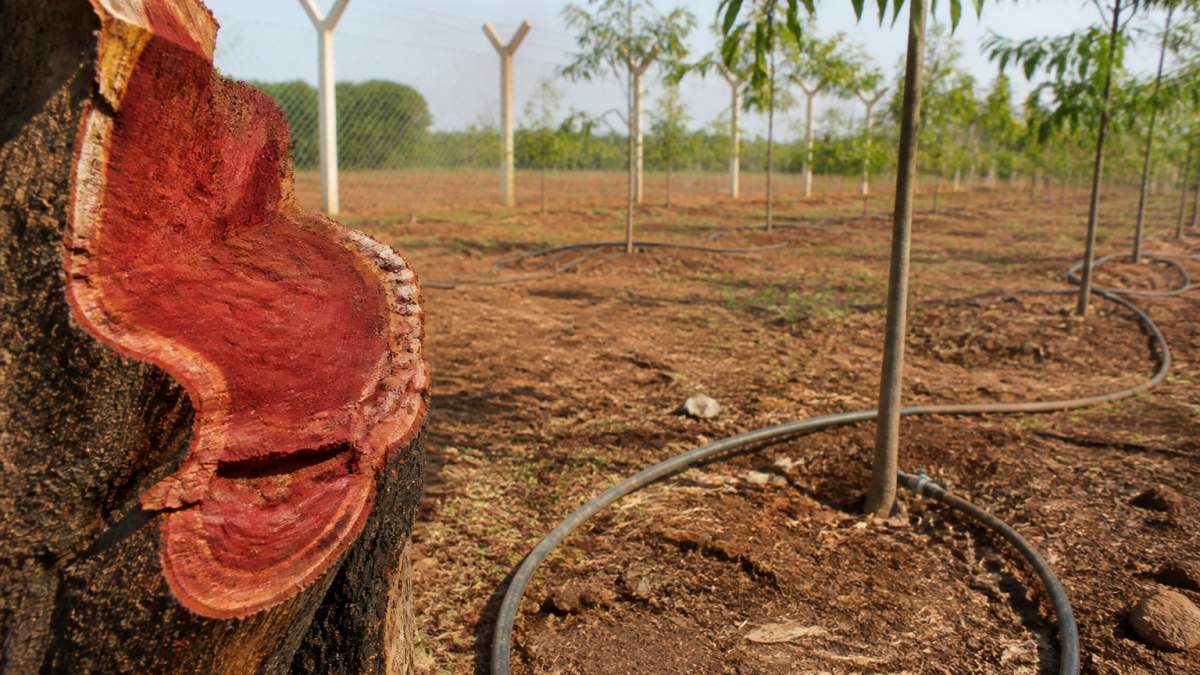
Red sandalwood is prized for its deep red heartwood. That makes documented ownership and a clean tax trail even more valuable at exit.
NRI Sale of Agricultural Land in India: Special Rules
An NRI sale of agricultural land in India is permitted, but acquisition rules are stricter than sale rules. Under FEMA, an NRI may not freely purchase agricultural land, farmland, or plantation property without specific approval.
That asymmetry creates a trap. Buyers who acquired farmland through a route that did not comply with FEMA can find the sale proceeds difficult to repatriate, because the bank traces the source of funds back to the original purchase.
This is precisely why documentation at the point of purchase decides your exit. When the time comes to sell, the acquisition trail is already clean and FEMA-compliant.
Step-by-Step Repatriation Process and Common Pitfalls
The end-to-end process from sale agreement to funds landing abroad follows a predictable sequence, but bank-level mechanics are where most guides stop short. Here is the workflow, with the decision points that matter.
- Confirm eligibility and the source of funds for the property. Verify the original acquisition complied with FEMA. If the property was inherited or gifted, assemble the succession certificate, will, or gift deed now, not at remittance time.
- Engage a chartered accountant early to compute capital gains and advise on holding-period timing. Ask specifically whether a Section 197 lower-deduction certificate is worth applying for.
- Apply for a lower TDS certificate if your actual liability is below the standard withholding rate. This runs in parallel with the sale, not after it.
- Complete the sale and register the deed, ensuring proceeds are credited to your NRO account. Confirm the buyer's TDS deposit and obtain Form 16A.
- Obtain Form 15CB from the accountant and file Form 15CA online. Keep the acknowledgment number; the bank will ask for it.
- Submit the full document set to your bank with a written repatriation request. Ask for the bank's own repatriation form and a named contact in the trade-finance or remittance desk.
- Track the exchange rate and bank charges before the bank executes the conversion. Request the bank's exchange spread in writing and compare against the interbank rate on the day.
- File your Indian and US tax returns, claiming foreign tax credit where applicable.
Bank-level mechanics and timelines. Authorized dealer banks route NRO repatriation through their trade-finance or remittance desk, not the branch counter. Document review typically takes one to three weeks when the file is complete, longer if escalated for source-of-funds review.
Troubleshooting a rejected or delayed remittance. Ask the bank for the specific compliance reason in writing. Most rejections trace to one of these:
- Mismatched names across passport, PAN, property documents, and NRO account. Fix the underlying record, not the remittance form.
- Incomplete tax filings, Form 15CA filed without a valid 15CB reference, or TDS not yet deposited by the buyer.
- Source-of-funds gaps, missing original purchase deed, inheritance certificate, or gift deed.
- Bank queries on the USD 1 million cap when multiple income streams are combined in the same financial year.
- Credits landing in an NRE account instead of an NRO account, which blocks property-sale repatriation.
Delays beyond the bank's stated window usually mean the file has been escalated for manual review, follow up with your relationship manager rather than resubmitting, which often restarts the clock.
Key Takeaway The single most common cause of a rejected remittance is a broken source-of-funds chain, not a tax problem. Fix the acquisition paperwork before you sell, and the repatriation becomes routine.Red sandalwood's deep red heartwood and tightening legal supply make documented, FEMA-compliant ownership a genuine exit advantage. So the paper trail you build at purchase is what protects the repatriation later.
Conclusion
Repatriating capital from Indian land sales is a documentation exercise more than a legal one. Sellers who prepare the acquisition trail, tax certificates, and bank file in advance move their money out smoothly; those who treat paperwork as an afterthought spend months in review.
If you are building an Indian land position you intend to exit cleanly later, start with an asset whose ownership is documented from day one. RedGoldAgro offers fully managed red sandalwood farmland with registered patta title and a 60/40 timber yield share at maturity, giving you a clear paper trail for future repatriation. Download our NRI Guide to see how the ownership and exit documentation works before you commit capital.
Frequently Asked Questions
Can an NRI repatriate money from the sale of land in India?
Yes, an NRI or OCI can repatriate sale proceeds from Indian land, but the rules depend on how the land was acquired and the seller's status. Proceeds from property purchased with foreign exchange and held in an NRE account are generally fully repatriable. For property bought with rupee funds or received as a gift or inheritance, repatriation is typically capped at USD 1 million per financial year (April-March) and requires an NRO account, a chartered accountant certificate, and Form 15CA/15CB. Agricultural land has additional restrictions, so verify eligibility with a CA before initiating the transfer.
What documents are needed to repatriate proceeds from an Indian land sale?
Banks typically require a completed remittance application, the sale deed and purchase deed, proof of property title, tax clearance or TDS certificates, Form 15CA and Form 15CB, a chartered accountant certificate, your passport and visa copies, PAN card, NRO account statements, and a declaration of the source of funds. For inherited or gifted property, include the will or gift deed and proof of the original owner's acquisition. Requirements vary by bank, so confirm the exact checklist with your remitting bank before submitting.
How much of the proceeds from an Indian property sale can an NRI repatriate?
The repatriable amount depends on the source of funds. If the property was purchased using foreign exchange remitted from abroad and held in an NRE account, the entire sale proceeds may be repatriable. For other cases, such as property bought with rupee funds or inherited assets, the NRO account repatriation limit is USD 1 million per financial year, subject to tax clearance and documentation. Note that capital gains tax and TDS are deducted before the net amount is considered, and the USD 1 million cap applies to the gross remittance, not the net after tax.
Are agricultural land sale proceeds eligible for repatriation?
Repatriation of proceeds from agricultural land sales is more restricted than residential property. Under FEMA rules, agricultural land is generally not freely repatriable unless it was acquired with foreign exchange or through specific exemptions. NRIs may need prior approval from the RBI or may only be able to remit funds from an NRO account up to the USD 1 million annual limit, after tax clearance. Because rules can change and individual circumstances vary, consult a chartered accountant and your bank before selling agricultural land to avoid delays or rejections.
Download NRI Guide